An insurance application can stall over a roof nearing the end of its useful life, an outdated electrical panel, or a plumbing material an insurer will not accept. A 4 point inspection gives the insurance company documented information about these major systems so it can evaluate the home’s risk. For Florida homeowners, it is often a practical requirement for obtaining or maintaining coverage, especially on older properties.
This inspection is focused, but it should not be treated as a formality. The findings can affect insurance eligibility, repair decisions, closing timelines, and the cost of ownership after a purchase. Knowing what the inspector evaluates helps owners, buyers, and agents prepare before an underwriter raises a question.
What Is a 4 Point Inspection?
A 4 point inspection is an insurance-focused evaluation of four essential home systems: the roof, electrical system, plumbing system, and heating and air conditioning system. The inspector documents visible conditions, approximate ages where they can be verified, materials, and signs of damage, deterioration, or unsafe installation.
Insurance carriers use this information because these systems are frequent sources of significant claims. A worn roof can lead to water intrusion. Aging electrical components can increase fire risk. Leaking pipes can damage walls and flooring over time. An inoperative HVAC system may point to deferred maintenance or moisture concerns in Florida’s humid climate.
The inspection typically results in a completed carrier form with supporting photographs. Every insurer has its own underwriting standards, so a condition that one company accepts may lead another to request repairs, additional documentation, or a different policy option. The inspector reports observed conditions; the insurance carrier makes the coverage decision.
The Four Systems Your Inspector Reviews
Roof covering and visible roof condition
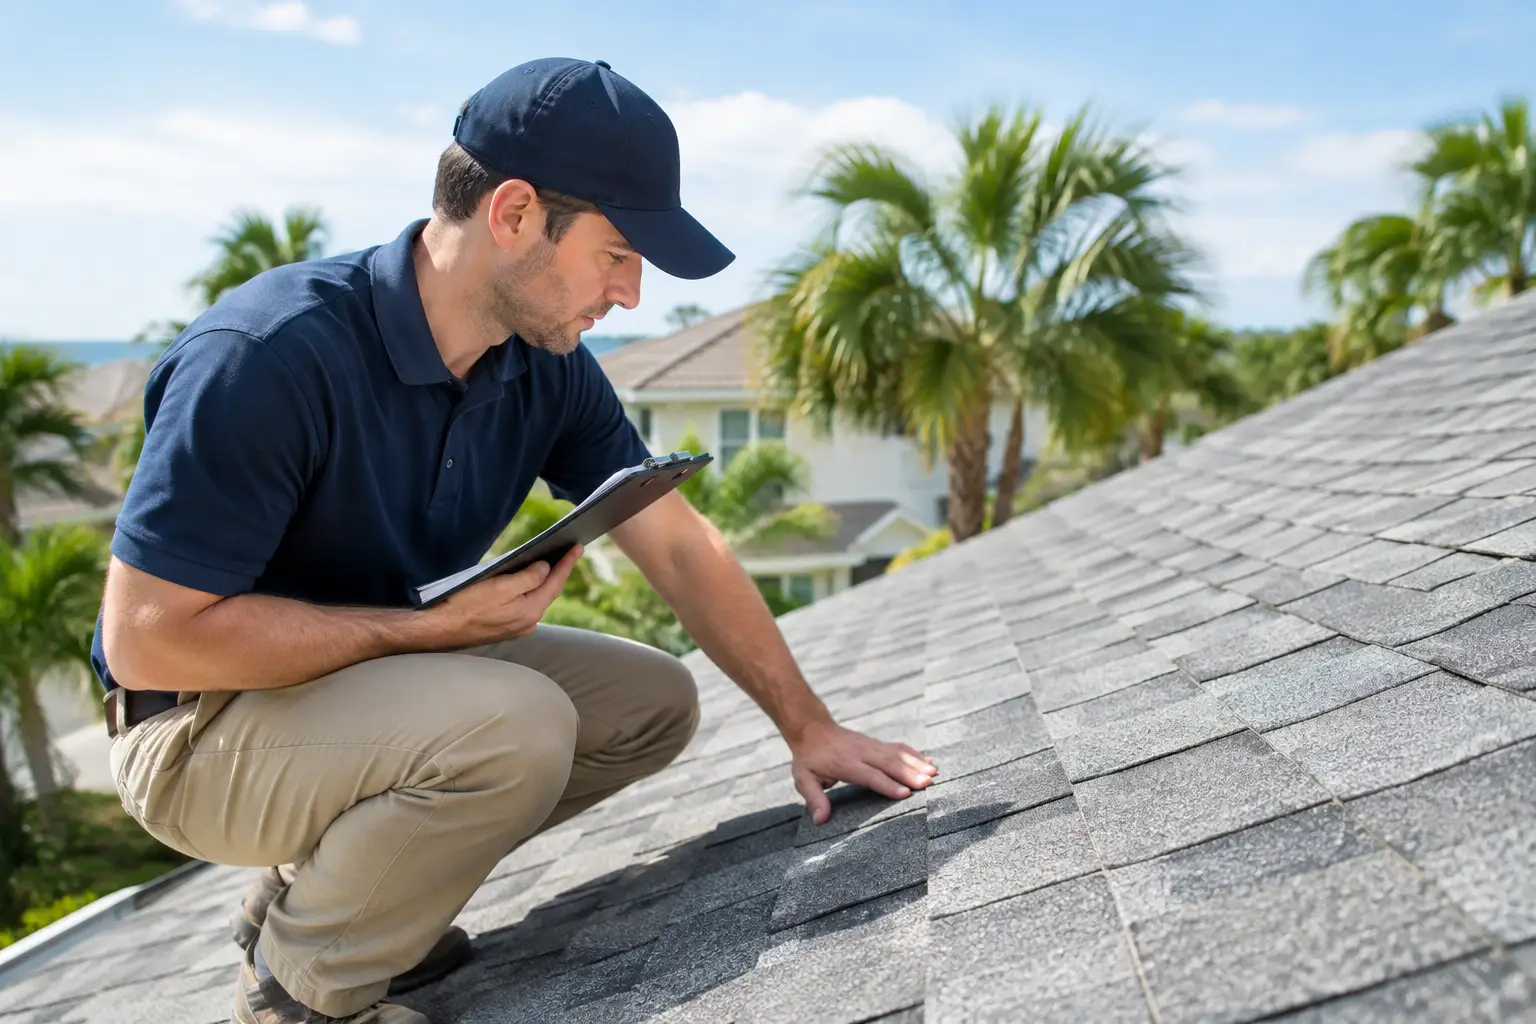
The inspector examines the roof covering from accessible areas and documents its apparent condition, material, visible defects, and evidence of prior repairs. Shingles, tile, metal, modified bitumen, and other roof types each age differently. A roof may not be actively leaking and still be a concern if it shows widespread deterioration, damaged flashing, missing materials, or extensive patching.
Roof age is often a major insurance question. Documentation from a permit, invoice, or prior report can be more reliable than a homeowner’s estimate, particularly when the roof has been replaced in stages or the property has changed hands several times. If records are unavailable, the inspector may be able to identify an approximate age or note that the age could not be verified.
A 4 point inspection is not a roof certification or a guarantee of remaining service life. If the roof shows concerns, a licensed roofing contractor may need to provide a repair estimate, certification, or more detailed evaluation.
Electrical panels, wiring, and safety concerns
The electrical portion generally includes the main service panel, subpanels when present, visible wiring, breakers, grounding, and observable defects. The inspector looks for issues such as corrosion, overheating, open panel knockouts, improper wiring methods, missing covers, or evidence of water intrusion.
Some older panel brands, wiring types, and installation conditions receive closer scrutiny from insurers. That does not automatically mean a home is unsafe or uninsurable, but it can affect underwriting. An insurer may request an electrician’s evaluation, repairs, or replacement of certain components before binding coverage.
Buyers should avoid assuming that a panel’s age alone tells the full story. A well-maintained system may have documented upgrades, while a newer panel can still have installation defects. Clear photographs and a thorough report give the insurer a better basis for review and give the owner a starting point for any needed electrical work.
Plumbing supply, drain, and water-heating components
For plumbing, the inspector identifies visible supply-line materials, drain and waste piping where accessible, water-heating equipment, and signs of active leaks or past water damage. Materials matter because some older pipe types have a history of failures or may fall outside a carrier’s underwriting guidelines.
A visible inspection cannot see inside walls, under every slab, or throughout concealed piping. It may identify a concern without determining the full extent of the issue. For example, staining under a sink may indicate a minor connection repair, while recurring water damage could warrant a plumber’s investigation or a sewer scope.
Water heater condition is also documented. Loose installations, corrosion, missing safety components, or leaking connections can create an immediate repair need. In a home sale, addressing these smaller, visible issues early can prevent them from becoming last-minute insurance or negotiation obstacles.
Heating, ventilation, and air conditioning
In Central Florida, air conditioning is not simply a comfort feature. It helps manage indoor humidity, which can influence moisture conditions and overall livability. The inspector documents the presence and apparent operating condition of heating and cooling equipment, along with visible damage, age information when available, and deficiencies that are apparent during the inspection.
An HVAC unit that does not operate, has a damaged disconnect, or shows substantial deterioration may require repair or replacement before an insurer will approve a policy. However, a 4 point inspection does not replace a full HVAC performance assessment. When a system is older, noisy, inadequately cooling, or showing signs of leakage, an evaluation by a qualified HVAC contractor provides a more complete answer.
Why Insurance Companies Request This Inspection
Many insurers request a 4 point inspection for homes that have reached a certain age, although the age threshold varies by carrier and policy type. The request may happen when purchasing a new policy, changing carriers, renewing coverage, or buying an older home.
The carrier is trying to understand the condition of the systems most likely to produce expensive claims. That makes this inspection different from a standard home inspection. A home inspection provides a broader overview of the property’s visible condition, including structure, appliances, interior components, and many other areas. A 4 point inspection has a narrower purpose: documenting insurance-related risk in four systems.
For a buyer, completing both inspections is often the better choice. The 4 point report helps with insurance underwriting, while a comprehensive home inspection helps reveal repair needs and maintenance priorities that could affect the purchase decision. One report should not be assumed to replace the other.
How to Prepare for a 4 Point Inspection
Preparation can make the appointment more efficient and reduce preventable report delays. Ensure the inspector can access the electrical panel, water heater, HVAC equipment, attic access when applicable, and exterior areas around the home. Remove storage or personal items blocking panels and equipment, and make sure utilities are on if the property is vacant.
Gather available records for roof replacement, HVAC installation, electrical upgrades, plumbing repairs, permits, and prior insurance inspections. These documents may not change what the inspector observes, but they can help verify ages and provide useful context to the insurance agent or underwriter.
It is also wise to correct obvious maintenance concerns before the inspection. Active leaks, missing panel covers, damaged roof materials, and unsecured water heaters are easier to address before they become part of an underwriting discussion. Do not conceal a problem, though. A repair should be completed properly and documented by the qualified professional who performed the work.
What Happens if the Report Identifies a Problem?
A concerning finding does not always mean coverage will be denied. The outcome depends on the system, its condition, the carrier’s rules, available documentation, and whether the issue can be repaired. The insurance company may approve coverage as submitted, request a contractor’s letter, require repairs within a defined period, or decline based on its underwriting guidelines.
If repairs are requested, obtain estimates from appropriately licensed professionals and keep invoices, permits, and final documentation. Once work is complete, the insurer may ask for updated photos, a repair invoice, or a reinspection. Acting promptly matters, especially during a real estate transaction with a pending closing date.
American Property Inspections helps Central Florida clients understand the documented condition of their property and provides clear reports that support informed conversations with insurance agents, contractors, and real estate professionals. The goal is not to create unnecessary concern. It is to identify visible conditions before they turn into a coverage delay or an expensive surprise.
A 4 point inspection is one small step in protecting a much larger investment. Schedule it early, keep your property records organized, and give yourself enough time to respond if the report identifies a repair that deserves attention.